The month is closed and the P&L shows a profit. Yet the bank account cannot cover the next supplier payment. The warehouse is full and customers owe a fair amount. Foreign managers running a distribution or production business in Uzbekistan often meet this picture in their first year.
Usually the problem is not profit but how long cash spends "in transit". This article shows how to measure the cash conversion cycle with three simple numbers. You will see what each day of the cycle costs you and get 7 practical ways to shorten it.
The topic is part of a wider system of financial discipline in a business. Discipline shows where money goes. The cycle shows where it gets stuck and for how long.
Why a profitable business runs out of cash
Profit and cash are different things. Profit is recorded on the day of the sale. Cash arrives on the day the customer pays. Weeks, sometimes months, pass between the two.
Purchasing works the same way. You pay the supplier today. The goods sit in the warehouse for a month, then go to a customer on credit, and turn into cash a month after that. All this time your money is working, but you cannot spend it.
This tied-up money is working capital. Put simply, it is inventory plus what customers owe you, minus what you owe suppliers. The larger it is, the more cash is frozen in stock and receivables.
The cash conversion cycle in three numbers
The amount moves with sales, so it is hard to compare month to month. Days are easier. That is what the cash conversion cycle (CCC) measures:
Also read Investment Incentives in Uzbekistan: Free Economic Zones, Small Industrial Zones and Investment AgreementsCash conversion cycle = Inventory days + Receivable days − Payable days
Each part has a plain meaning:
- Inventory days — how long goods stay in stock on average. In manufacturing this covers raw materials, work in progress and finished goods.
- Receivable days — how many days after delivery the customer pays. Receivables are money others owe you.
- Payable days — how many days after delivery you pay the supplier. Payables are money you owe others.
The cycle answers one question: how many days pass between paying a supplier and getting the money back from a customer? You finance those days yourself.
A cycle can also be negative. A shop where buyers pay at the till sells quickly and pays its supplier later, so growth brings in more cash. In wholesale and manufacturing the cycle is almost always positive.
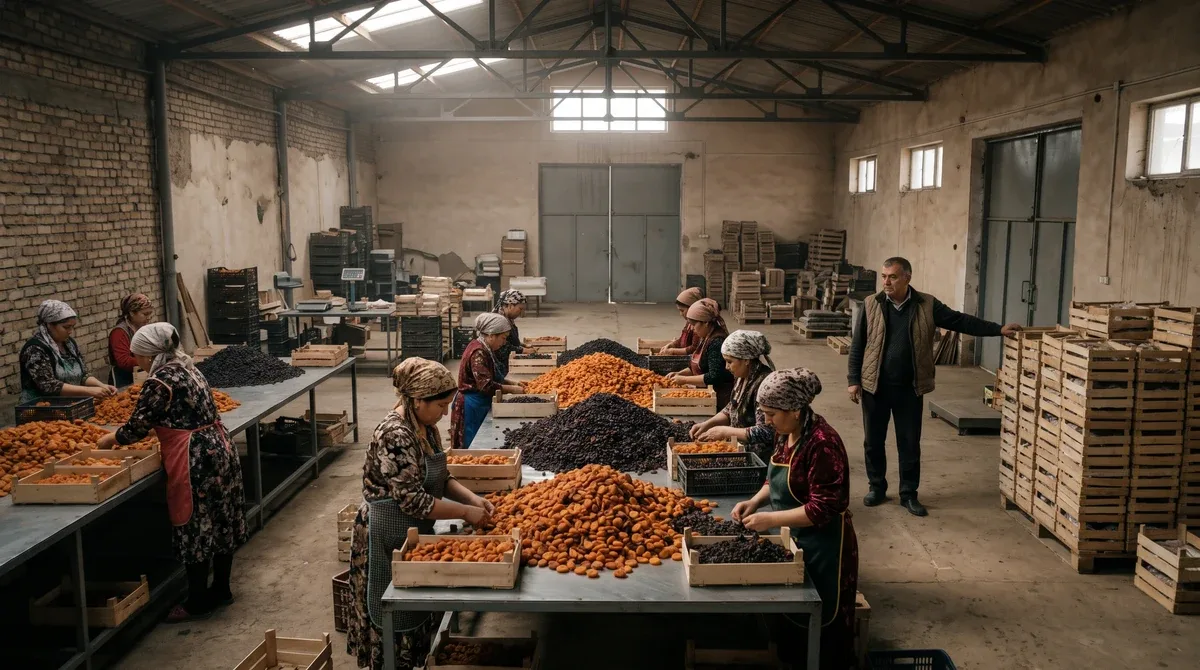
Illustrative example: a wholesale distributor
This is a hypothetical example with round numbers. Say your company supplies household cleaning products to retail shops. Monthly revenue is 300 million UZS and the cost of goods sold is 240 million. After all expenses, about 25 million UZS of net profit remains.
Here is the cycle step by step. For balances, use the average of the start and end of the month. Inventory and payables are carried at cost, so they are divided by daily cost of goods. Receivables are at selling price, so they are divided by daily sales.
- 1. Daily cost of goods — Calculation: 240 m ÷ 30 days; Result: 8 m UZS
- 2. Daily sales — Calculation: 300 m ÷ 30 days; Result: 10 m UZS
- 3. Inventory days — Calculation: average stock 360 m ÷ 8 m; Result: 45 days
- 4. Receivable days — Calculation: shops' average debt 300 m ÷ 10 m; Result: 30 days
- 5. Payable days — Calculation: average debt to suppliers 120 m ÷ 8 m; Result: 15 days
- 6. Cash conversion cycle — Calculation: 45 + 30 − 15; Result: 60 days
Where do the numbers come from? Take stock from your accounting system or the latest stock count, valued at cost, not at selling price. Take receivables and payables from customer and supplier debt lists. If those lists are out of date, reconcile balances with your largest counterparties first. For a quarter, divide by 90 days instead of 30.
The result: every som you pay out comes back after 60 days on average. Cash frozen in operations is 360 + 300 − 120 = 540 million UZS. That is more than twenty months of profit, funded either by your own equity or by debt.
Now the useful part: what is one day worth? Cut inventory by 10 days and 10 × 8 = 80 million UZS is released. Cut receivables by 10 days and you free 100 million. No new sales needed, only speed.
What are these three numbers in your business? When did you last calculate them?
The growth trap: why more sales can mean less cash
This catches many owners and country managers off guard. Growth feels like it should bring more cash. In reality, if the cycle stays the same, growth has to be paid for first.
Back to the example. Sales rise by 30% to 390 million UZS a month. If the days stay the same, frozen cash also grows by 30%: 540 × 1.3 ≈ 702 million. You need an extra 162 million.
Profit grows too, say to 40 million a month. But covering the 162 million absorbs roughly four months of profit (162 ÷ 40 ≈ 4). For those four months there is almost no spare cash in the account, even though the reports look good.
So before a big contract or a new branch, ask one question: where will the working capital for this growth come from? A payment calendar helps answer it in advance by showing the week when a cash gap will appear.
Manufacturing and marketplaces: what changes in the cycle
The formula is the same for everyone, but the heavy link differs.
In manufacturing inventory has three layers. Raw materials wait in the warehouse, semi-finished goods wait on the shop floor, and finished goods wait for shipment. Most cash usually gets stuck in raw materials bought in bulk "to save money". The discount is a few percent, while the cash is locked up for three months. If inputs are imported and paid in foreign currency, a long cycle also means a longer currency exposure.
In wholesale the heavy link is usually receivables. Supplying shops on deferred payment is a common local practice, and terms tend to stretch over time. How to handle overdue debts step by step is covered in collecting overdue debts.
On marketplaces the platform payout period replaces receivables. You cannot negotiate it, so always check the exact term in the current seller offer. A separate calculation with examples for sellers is in working capital for marketplace sellers.
7 ways to shorten the cycle
Each method removes days, and days turn into cash. Start with the link that has the largest number.
- Clear slow-moving stock. List items that have not moved for more than 90 days. Sell them at a discount, in bundles or to another reseller. Selling slightly below cost beats waiting a year for the cash.
- Order smaller batches more often. Set a minimum and maximum stock level for each item. A batch bought "just in case" is usually the one that sits longest.
- Give customers a credit limit and term. Put the amount and the payment term for each customer in writing. When the term is overdue, new shipments stop. Ask new customers for partial prepayment.
- Send documents on time. If the electronic invoice or the reconciliation statement is late, payment will be late too. This method costs nothing but is often forgotten.
- Price early-payment discounts carefully. Say you offer 2% off for paying in 10 days instead of 40. You collect 98 instead of 100, but 30 days sooner. That works out to about 25% a year (2 ÷ 98 × 365 ÷ 30), or around 28% with compounding. If a bank loan is cheaper, the discount costs you more.
- Negotiate longer terms with suppliers. Do not delay payments unilaterally: that leads to penalties and lost trust. With a record of paying on time, asking for longer terms is much easier. More on this in managing accounts payable.
- Reduce batch sizes in production. Buy raw materials in stages and do not let semi-finished goods sit on the floor. If you can produce to order, the finished-goods warehouse shrinks as well.
You do not have to do everything at once. Pick one method and recalculate the cycle a month later.
Red flags: signs the cycle is slipping
A red flag is not a problem in itself, but it is a reason to check:
- reported profit is growing while the bank balance is shrinking;
- receivables grow faster than sales;
- the share of stock older than 90 days rises every month;
- late payment to suppliers has become routine;
- short-term loans are taken to cover salaries or taxes;
- the cycle has lengthened two or three months in a row.
If two or three signs appear together, open the cycle table and find which link has grown. Updating it once a month on a fixed day takes 15–20 minutes.
Conclusion: speed is also a source of cash
When a profitable business lacks cash, slow turnover is often the cause. Money gets stuck in the warehouse, in customer debts and in large batches. The cash conversion cycle shows this in one number: inventory days plus receivable days minus payable days.
Convert each day into money and the priorities become obvious. Before planning growth, calculate how much working capital it will require.
Take one step today: calculate your cycle from last month's figures and find the longest link. Starting there frees up the most cash.
Frequently asked questions
What is working capital in plain terms?
It is the money a business keeps tied up in stock, raw materials and customer debts so it can keep operating day to day. In simple terms: inventory plus what customers owe you, minus what you owe suppliers. The bigger this number, the more cash is frozen in operations.
What is a normal cash conversion cycle?
There is no single benchmark. A shop that sells for cash can have a short or even negative cycle, while manufacturing and wholesale run much longer. Compare yourself with your own previous months: if the cycle keeps growing, find out why.
How often should the cycle be measured?
Once a month, after the books are closed, is enough. When sales are growing fast or a peak season is starting, a check every two weeks is useful. What matters is using the same method every time.
If working capital runs short, should the business borrow?
First check whether the cycle can be shortened: excess stock and overdue receivables are often a cheaper source than a loan. Borrowing makes sense when the cycle is under control and the interest is lower than the profit from extra sales. Check current terms directly with banks in Uzbekistan before deciding.
Want to see where your cash is stuck in Uzbekistan?
We can calculate your cash conversion cycle together from the last three months of figures and calmly work out which link to fix first to free up the most cash.